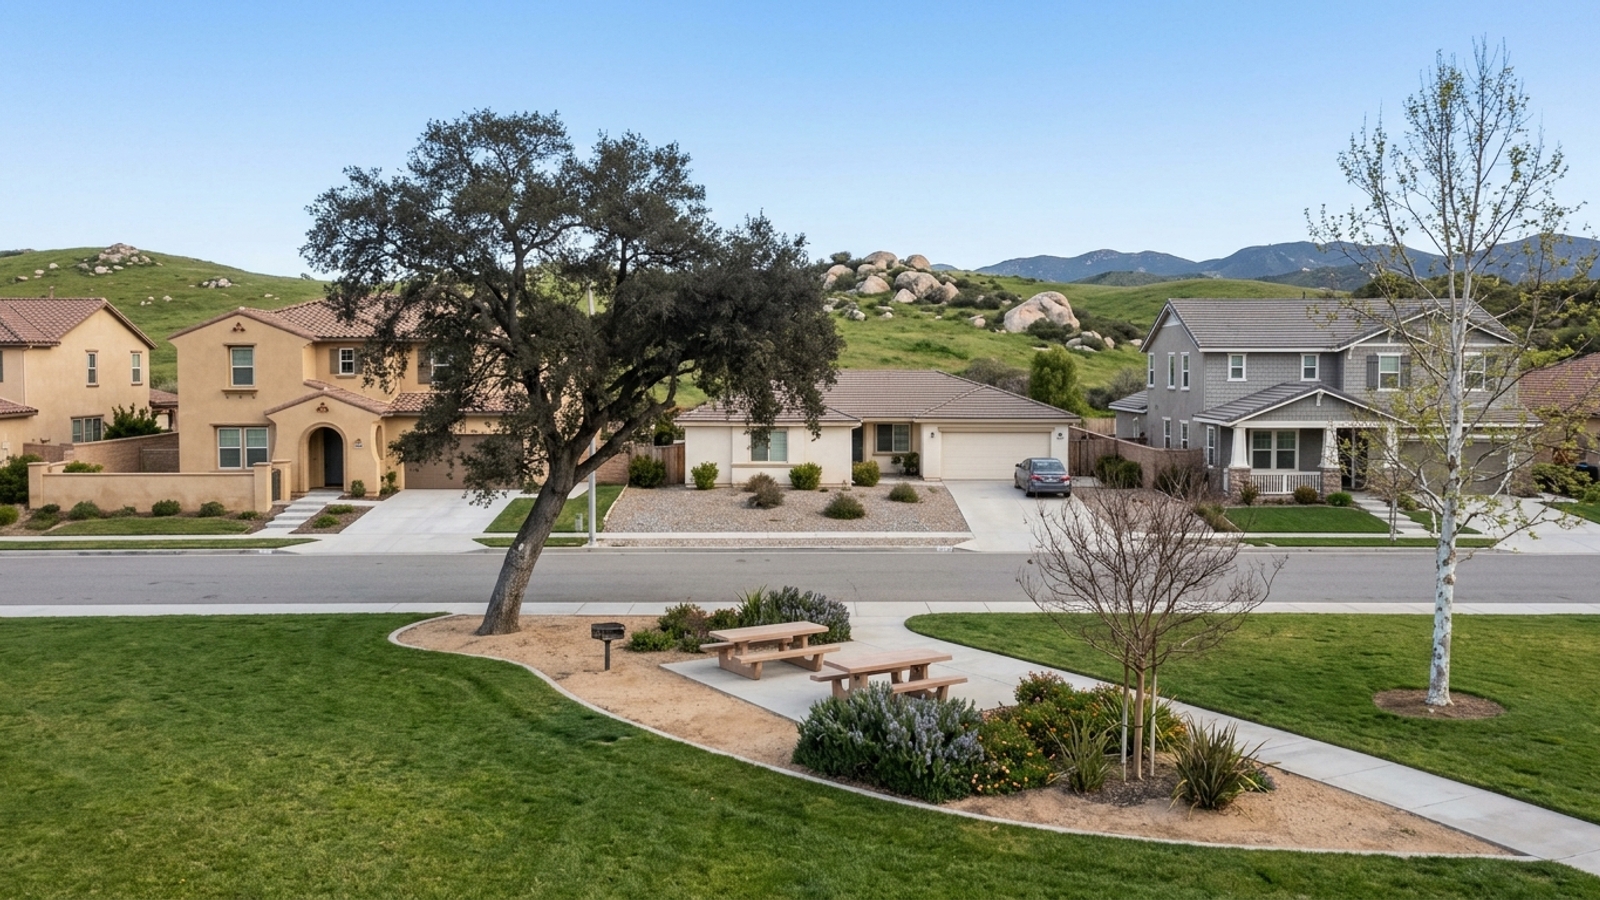
The median sale price for a home in Temecula, CA, is currently around $735,900, up less than 1% from a year ago.
Key takeaway
Expect Temecula home prices to stay roughly flat rather than fall. House values rose less than 1% over the past year, and supply is still tight. If you need a house, buying on your own timeline and negotiating terms beats waiting for a drop. The alternative is a condo: the headline price decline rests on a thin sample, but slower condo sales give you more time to negotiate.
Who this guide is for
You’re deciding whether to buy or sell a Temecula home in the next 12 months or hold off, and want to know how much the current numbers should change your timing, price or offer.
What is the Temecula housing market forecast?
Home prices in Temecula are not dropping; they are holding flat. House values barely moved over the past year. With 3.7 months of supply, listings aren’t piling up, so there’s no backlog forcing sellers to cut prices across the board. The one falling figure, the condo median, rests on a thin sample, and the house-and-condo comparison below explains why it overstates the discount.
State-level projections point to the same holding pattern. The California Association of Realtors released its baseline 2027 forecast on October 7, 2026. It projects existing single-family home sales to rise 3.7% statewide next year, with the median price rising 1.4% to $894,400.
Local market data changes month to month, so check the latest figures before you price an offer or a listing. Twelve-month forecasts are estimates to plan around, not financial advice to bet a purchase on.
Factors that could shift the 2027 outlook
Three main signals could move this trajectory:
- Borrowing costs: these set local purchasing power. As of October 29, 2026, Freddie Mac reported the 30-year fixed-rate mortgage averaged 7.24%, and the mortgage rate you’re quoted changes what you can afford more than any price shift.
- Active inventory: if listings climb while sales hold steady, the advantage shifts further toward buyers.
- Local jobs: employment supports housing demand. The California EDD reported a 5.9% unemployment rate for Riverside County in September 2026.
Temecula housing market at a glance
- Median sale price, all homes: $735,900, up 0.8% year over year (90 days ending Sept. 30, 2026)
- Median sale price, single-family: $748,702, up 0.5% year over year (90 days ending Sept. 30, 2026)
- Median sale price, condos: $479,951, down 17.2% year over year (90 days ending Sept. 30, 2026; based on only 13 condo sales, so treat with caution)
- Homes sold: 318 all homes, 298 single-family, 13 condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
- Median days on market: 45 all homes, 44 single-family, 54 condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
- Sale-to-list price: 99.7% all homes, 99.6% single-family, 100.1% condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
- Share sold above list: 28.1% all homes, 29% single-family, 15.4% condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
- Months of supply: 3.7 all homes, 3.5 single-family, 6 condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
- Homes for sale (inventory): 386 all homes, 336 single-family, 26 condos (90 days ending Sept. 30, 2026; condo sales figures based on 13 sales)
- Median price per square foot: $354 all homes, $354 single-family, $358 condos (90 days ending Sept. 30, 2026; condo figure based on 13 sales)
Single-family homes vs condos in Temecula
The trade-off is a house at flat, firm prices versus a condo whose headline price drop is less of a discount than it looks.
Single-family houses
Houses make up most Temecula sales, and their values are firm. Prices rose just 0.5% year over year, yet about 29% still sold above asking. A fresh, well-priced listing can still draw competition, so a lowball offer on day one risks losing the property.
Your bargaining power lives in houses that have sat past the median days on market. That’s where you negotiate terms: seller credits, repairs, a favorable closing date. The catch is that flat prices don’t mean soft prices. Waiting for a discount on the exact right house can cost you the house.
Condos and townhomes
The condo median sale price fell 17.2% year over year, but that figure rests on just 13 sales that still closed at 100.1% of asking. Per square foot, condos sold at $358 versus the single-family median. The lower median most likely reflects smaller units changing hands, not sellers slashing prices. A condo buys a lower entry price, not a bargain rate.
Slower condo sales give you more time to compare units. Before you weigh a condo against a house, ask the HOA for current monthly dues, the latest reserve study and any planned special assessments. For an FHA or VA loan on a condo, confirm the project’s approval status on the HUD or VA condo lookup.
The catch: the slow pace that works in your favor as a buyer works against you when you sell. Condos carry more supply and longer days on market than houses, and HOA dues add to every month you own.
Should you buy now or wait?
One year of appreciation at the recent pace adds about $3,700 to the single-family median of $748,702. If you put 10% down, your loan is $673,832. A half-point change in your mortgage rate moves the monthly principal-and-interest payment by about $220, which is roughly $2,600 a year.
Get a current rate quote from your lender and rerun the example with your own down payment and rate. Set your price ceiling from the monthly payment your income supports, not from the list price. Down payment assistance programs can cover part of the upfront cash for eligible buyers. Budget for buyer closing costs on top of your down payment.
If you need to move, the rate you lock and the terms you negotiate matter more than the current price trend. Waiting only pays off if rates fall meaningfully, which no one can promise.
What the forecast means for Temecula sellers
The median time on market for all homes is currently 45 days. Plan for about six weeks on market plus your escrow period when you map out your selling timeline or a concurrent purchase. Condo sellers should expect a slightly longer timeline.
Flat prices mean pricing to recent comparable sales matters from day one. The houses that sell above list (see the single-family figures above) are generally the ones priced right when they hit the market. A property valuation shows where your home stands against those comps.
Weigh home staging before listing photos are taken. Estimate your net proceeds after seller closing costs and the commission rate you agree to. Temecula has fire hazard zones, so review your seller disclosure obligations before listing. If you’re also buying, check each listing’s days on market and price-change history before deciding how hard to negotiate.
If you want a specific assessment of your property, Josh Painter at Impact Real Estate can prepare a pricing review.
How to use this forecast
If you need to move within the next year, start with “Should you buy now or wait?” Flat prices mean waiting saves little, and the worked example shows why the rate you lock matters more. If you’re choosing between a house and a condo, “Single-family homes vs condos in Temecula” shows why the condo price drop is less of a discount than it looks. If you’re selling within the year, “What the forecast means for Temecula sellers” covers timeline and pricing. If a small rate change decides your budget, run the worked example with your own numbers and check current mortgage rates before you set a price ceiling.
Temecula housing market forecast FAQs
Is it expensive to live in Temecula, CA?
Yes, compared with many states, but homes cost less than the California benchmark. C.A.R. put the statewide median for an existing single-family home at $887,680 in July 2026, above Temecula’s median. Property tax and utilities add to the monthly cost of living beyond the mortgage.
What is the hardest month to sell a house in Temecula?
Local sales volume slows during the late fall and winter holidays. Ask your agent for 12 months of local days-on-market data by month before choosing a list date.
Are there any lots for sale in Temecula, CA?
Yes, vacant land does come on the market. Before making an offer, confirm water and sewer availability with the local utilities, check the seller disclosures for fire hazard zones and ask whether the lot carries a Mello-Roos special tax.
How much is rent in Temecula, CA?
Rent varies with property size and neighborhood. HUD’s Fair Market Rent for Riverside County gives baseline estimates for two- and three-bedroom units. If your rent approaches the payment in the buy-or-wait worked example, buying may be the better financial move.
Will mortgage rates go down in 2027?
The Mortgage Bankers Association expects 30-year fixed rates to average 7.3% in Q4 2026 and stay above 7% through 2027. That makes the rate you lock a bigger factor in your budget than the price trend.
Is Temecula a buyer’s or seller’s market right now?
By the industry rule of thumb, six or more months of supply favors buyers and three months or less favors sellers. Temecula’s single-family market leans slightly toward sellers, while condos sit closer to the buyer’s threshold (see the supply figures at a glance).
How many new homes are being built in Temecula?
Temecula’s allocation for 2021-2029 is 4,193 units: 1,359 very low-income, 801 low-income, 778 moderate-income and 1,255 above moderate-income. The figures come from the Housing Element HCD approved on December 15, 2022. This planned supply could eventually ease today’s tight inventory.
Do Temecula homes have Mello-Roos taxes?
Some do. A Mello-Roos Community Facility District adds a special tax on top of normal property tax to repay bonds that fund improvements such as streets, water and schools. The city’s active districts include Harveston, Harveston II, Crowne Hill Series A and B, Roripaugh Ranch, Roripaugh Ranch Phase 2, Wolf Creek and Heirloom Farms. Ask the seller or title company for the property’s annual special tax amount and payoff date.
Sources
- Redfin: Data Center
- California Association of Realtors: 2027 Housing Forecast
- Freddie Mac: Primary Mortgage Market Survey
- California EDD: September 2026 Unemployment
- California Association of Realtors: July 2026 Home Sales
- Fox Business: Key hurdle for homebuyers may stick around through 2027
- The Real Deal: Is the buyer’s market dead and gone for California homes?
- City of Temecula: Housing Element
- City of Temecula: Debt Management